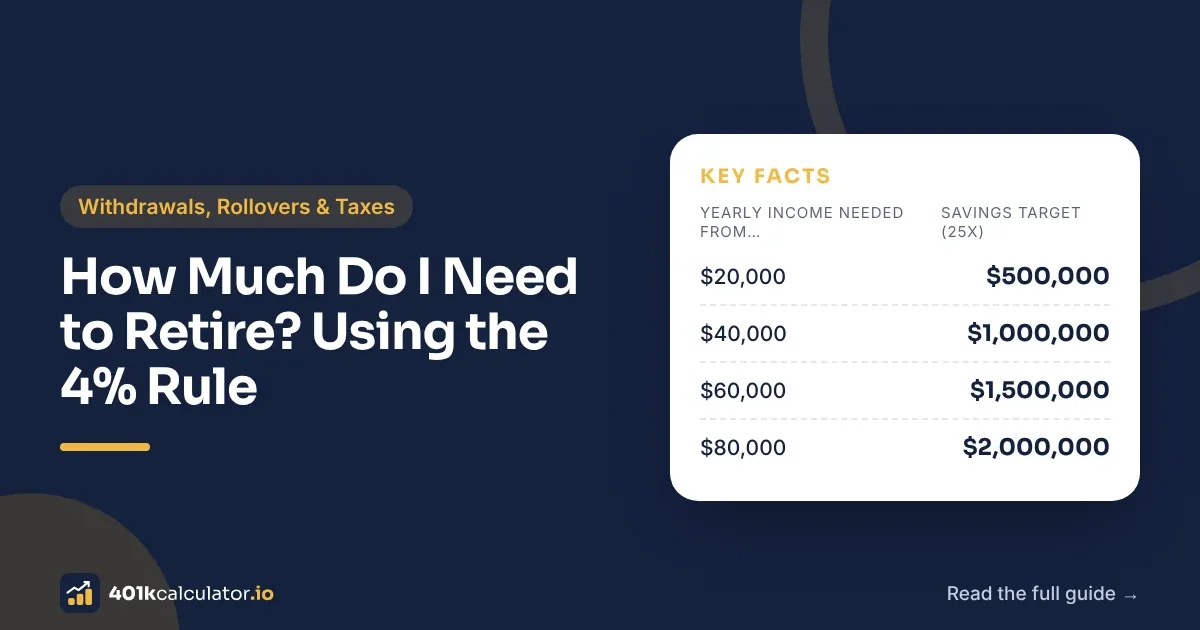
The 4% rule is a common starting point: in your first year of retirement, withdraw 4% of your savings, then raise that amount with inflation each year. Turned around, it says you need about 25 times the yearly income you want from your savings.
Step 1: Estimate Your Spending
Many people need somewhere around 70–80% of their pre-retirement income, but your own budget is the best guide.
Step 2: Subtract Guaranteed Income
Subtract Social Security and any pension. You can estimate Social Security with your statement at ssa.gov/myaccount.
Income needed from savings = Yearly spending − Social Security − Pension
Step 3: Multiply by 25
| Yearly income needed from savings | Savings target (25x) |
|---|---|
| $20,000 | $500,000 |
| $40,000 | $1,000,000 |
| $60,000 | $1,500,000 |
| $80,000 | $2,000,000 |
Example: you expect to spend $65,000 a year and get $25,000 from Social Security. You need $40,000 from savings, so your target is about $1,000,000.
Step 4: Compare With Your Projection
Enter your details in our 401(k) calculator. It shows estimated yearly income at a 4% withdrawal rate. Compare in today’s dollars so inflation doesn’t mislead you. See Inflation and Your 401(k).
Limits of the 4% Rule
- It came from studies of historical U.S. market returns over 30-year retirements. Future returns may differ.
- Retiring early means a longer retirement, so a lower withdrawal rate may be safer.
- It ignores taxes. Traditional 401(k) withdrawals are taxed as income, so you may need to withdraw more to spend the same. See How 401(k) Withdrawals Are Taxed.
- Real spending isn’t steady. Healthcare costs often rise later in life.
Treat 4% as a planning estimate, not a guarantee.
FAQs
Is 4% too high or too low? It depends on your investment mix, retirement length and flexibility. Many retirees adjust withdrawals after poor market years.
Does the 4% include required minimum distributions? RMDs are separate tax rules. If your RMD is larger than what you’d spend, you must still withdraw it, but you can reinvest it in a taxable account.
Sources: Social Security Administration – my Social Security · Calculations by 401kcalculator.io.
Last reviewed: 20 Nov 2026 · Written and fact-checked by Zeeshan Nawaz